Exit Planning Tools for Business Owners

When Kids Don’t Cut It

Many owners want to see their children inherit the business, but what happens when the kids don’t cut it?

Some years ago I worked with a business owner whose exit plan was to sell into one of the private equity roll-ups that were active in his industry. His son was finishing college, where he studied for a career in wildlife management. The son’s ambition was to spend his life in the great outdoors.

One day my client was beaming when I walked into his office. “Guess what?” he said. “My son called. He wants to take over my business!” After a few minutes, it was pretty clear that we weren’t going to have a conversation about experience or qualifications. This owner had a whole new exit plan.

Fortunately, that plan worked out. There was strong management in place, and the son paid his dues in sales and management training before the transition. Not all such shifts work out that way.

When kids don’t cut it
when the kids don't cut itThere was another prospect who gave me my “assignment” for proposing. “My son has been in the business for the last ten years. He seldom shows up. He is nominally in charge of a department, but we do little or no business in that area. He’s abusive when he is here, and all the employees hate him.”

“We (his mother and I) want to sell him the business, and we need him to perform well to fund our retirement. How much will you charge to straighten him out and get him to run the business right so he can pay us?”

I wanted to answer “Infinity,” but chose instead to politely decline the engagement.

I’ve written many times about the attachment a founder has for his or her business. Of course, parents (hopefully) have an even stronger bond with their children. Watching the first client’s face light up when he made the announcement was the best illustration of how important legacy preservation can be to an owner.

Yet, keeping the business in the family isn’t always the best idea. It involves a number of stakeholders, including employees and other children.

Key Employee Issues

For brevity, we will start by presuming that you’ve never promised, indicated, discussed, or even hinted to key employees that they were going to own the company. If you have, that’s a whole different can of worms that we’ll deal with another time.

We also aren’t talking about a succession plan where the son or daughter has always been the heir apparent, and has trained for the position.

Commonly, it’s somewhere in between. The child holds a job in the company, but not the second-in-command position. He or she does it well enough, but isn’t a star. They are interested in ownership (another too-often ignored question,) but their ability to act as CEO in the foreseeable future is doubtful.

Even if key managers aren’t resentful, they are not chattels. Giving ownership to a child is a clear message that their career path has reached a stopping point. It may be an eye-opener, and almost certainly disposes them to look at other opportunities, even if they don’t do so actively. Remember, their loyalty is to you. It isn’t automatically transferrable.

One solution that’s often employed is the perpetuation of the founder/owner. He stays on in a consulting role long after normal retirement age. Often it works out, and it can lend tremendous experience to the company.

If you don’t want to stick around in the “answer man” role, however, you need to secure the continued commitment of the key managers. That should be done through conditional compensation, tied to the continued success of the company. If appropriate, it may also require reaching benchmarks for training the offspring to take the reins of the business.

Long-term compensation can be through virtual equity (Phantom Stock or Stock Appreciation Rights,)  direct profit participation, actual minority equity ownership, or supplemental retirement insurance. It needs to be more than just a salary, though. Someone else can always beat a salary.

Keep Thanksgiving Friendly

The other stakeholders who should be considered are the siblings who don’t work in the business. Often the owner wants to leave the business to the child who has worked in it. The owner’s spouse wants to divide it equally among all the children. Both ways are fraught with issues.

Leaving the entire income-producing capability of the family (the company) to one child can obviously create resentment. On the other hand, forcing that child into a lifetime of working for the benefit of his or her siblings is likely to end family Thanksgivings. No one wants to grow a business only to see a third, or half or three-quarters of the benefit go to bystanders.

Some owners choose to balance their estate with other assets outside the business. If that isn’t practical, we frequently recommend dividing the business equally, but with a valuation formula and documented agreement to sell the inherited shares to the active child or children. Everyone benefits from the parent’s work, but going forward the active child keeps any increase in profits (and also bears the risk of any decline.)

Passing the legacy of a successful enterprise to children can be one of the greatest thrills of a parent’s life. When the kids don’t cut it, however, it is wise to face facts and plan accordingly.  Glossing over the issues will inevitably lead to more pain down the road.

John F. Dini, CExP, CEPA is an exit planning coach and the President of MPN Incorporated in San Antonio Texas. He is the author of Your Exit Map: Navigating the Boomer Bust, and two other books on business ownership. If you want to see how prepared you are for transition, take the 15-minute Assessment at MPNInc.com/ExitMap. 
 

An Often Neglected Means Of Protecting Business Value

one glass half full, one glass empty

Protect The Business Most Valuable Asset

A compelling and common characteristic of successful business owners is optimism. The “glass is always half full” attitude results in the risk-taking, perseverance, and innovation it takes to build, grow, and protect a successful business. Like any personal strength, this optimism can quickly become a weakness when there is a need to plan for the gloomy business contingencies of death and disability. What happens to the business due to either of these less than optimistic events is the last thing an optimistic owner wants to think about.

Some might say that perhaps owners don’t care if the business fails due to their inconvenient incapacitation. However, our experience shows that most owners care about what happens to the business and its stakeholders. We also observe that the plan in place is often deficient. For example, one area most often overlooked is preparation for the owner’s potential permanent disability.

Is The Business Owner Protected?

It is fairly common for a business owner to have a level of life insurance protection (although often outdated or in need of review) to benefit their business as well as their family in the event of death. But it is not nearly as common to see the risk of permanent disability addressed adequately, if at all.

Becoming disabled for more than three months are greater than the chances of dying at every age:
     • Over one in four 20-year-olds will become disabled before reaching age 67. (1)
     • At Age 30 – the chances of disability are approximately 2.3 times greater than death
     • At Age 40 – the chances of disability are about twice that of death
     • And finally, at Age 50 – disability is 50 percent more likely than death (2)
     • Not only does the risk of disability rise as we get older, but the severity of any disability that is incurred also tends to increase with age (3)

Permanent disability (or death) and incapacitation would most likely have the same impact on your business as the loss of any key employee would have. All that you bring to the table makes the business a success. Experience, talents, knowledge, and relationships would all be tough to replace. There could also be additional challenges such as the loss of concerned stakeholders, weakening financial strength, bank financing re-examined, bonding capabilities interrupted, potential non-renewal of personally guaranteed leases, etc. All as a result of your not being able to work in the business.

Protect Business Value. Have a Plan.

The bottom line is, in the event of premature permanent disability or incapacitation, the value of the business could decrease significantly. All stakeholders are impacted. And the family, if dependent on the continual success of the business, is impacted similarly. Make sure to thoroughly thought through this risk with an insurance professional. Too often, it’s neglected entirely. Please note, you can contact us for any assistance needed.

Invest 15 Minutes and take our FREE Exit Readiness Assessment. We do not request any confidential information.

Pat Ennis is the President of ENNIS Legacy Partners (ennislp.com). The mission of ELP is to help business owners build value and exit on their own terms and conditions.

Endnotes:
(1) The Facts about Social Security’s Disability Program, Social Security Administration Publication No. 05-10570, January 2018.
(2) 1985 Commissioners’ Disability Individual Table A and 1980 Commissioners’ Standard Ordinary Mortality Table.
(3) Americans with Disabilities: 2010, U.S. Census Bureau, Current Population Reports, July 2012.

Succession Planning or Exit Planning? Small Business Owners Need Both!

4 business persons with the words succession planningOne of the questions we often hear from business owners is, “What is the difference between Succession Planning and Exit Planning?  Aren’t they the same thing?”  Surprisingly, they are not.  The next question usually is, “Which one do I need?” The answer is simple.  Whether the business is small or large, family-owned or not, astute business owners always need both.

succession planNearly $10 trillion dollars in business assets will be transferred globally in the next decade, according to Forbes Magazine.  Baby Boomers selling privately owned businesses or transferring them to family members will comprise much of that $10 trillion dollar transfer.  As the market becomes crowded with owners ready to sell, the advantage will go to those owners who have done their due diligence, considered all of their options, and planned for unexpected contingencies.
Succession Planning

Succession Planning focuses solely on transferring leadership inside the business from one generation to the next.  Succession plans identify key individuals within the organization who can be trained and mentored to someday take over as the existing business leaders exit.  Succession Planning is just one necessary aspect of a more comprehensive exit plan.

Exit Planning

Exit Planning incorporates succession planning with strategies for building transferrable value, reducing tax liability, preparing for unexpected contingencies, minimizing family stresses, and increasing the likelihood of a successful business transfer.  Exit plans also incorporate the personal and financial goals of the business owner, their spouse, and their family.  A prudent exit plan starts and ends with the long term business and personal objectives of the owner.

Plan Ahead for A Successful Exit

Succession plans and exit plans so share an important characteristic – neither should wait.  Business owners who eventually want to sell for top dollar with the least amount of trouble must start the planning process early enough to give it the thought and consideration it requires.   With the proper plans in place, you, the business owner, gains the ability to make critical long-term decisions that will significantly increase the likelihood of selling or transferring the business when you want, to whom you want, and for the price you want.

Pat Ennis is the President of ENNIS Legacy Partners (ennislp.com). The mission of ELP is to help business owners build value and exit on their own terms and conditions.

Exit Planning in a Crisis

Why would you be exit planning in a  crisis? At the height of the economic expansion (a few months ago in late 2019) I was reviewing a company’s financial statements. Their sales were stagnant, and profits were minimal. When I asked the owner why his business hadn’t grown, he responded, “Well, the Great Recession hit our industry pretty hard, you know.”

planning in a crisisTake note that it wasn’t his fault. He was in a hard-hit industry, and the economy dealt him a bad hand. He ignored the thousands of businesses just like his that had grown and prospered in the last ten years.

Once you hunker down behind “It’s not my fault,” it’s easy to stay there too long. First you are glad that you survived. Then you are glad to be making a little bit of money again. Then you wait for the same conditions that made you successful before. If they don’t come, it’s not your fault.

In the meantime, others are coming out of the downturn firing on all cylinders. They used the slow time to get ready; to plan what comes next. When the door of opportunity opened again, they were ready.

Baby Boomers’ Double Whammy

The coronavirus is especially lethal in senior citizens. Many of those are Baby Boomer business owners. They have also suffered a double financial hit. Their retirement account balances are lower, and their businesses, whether closed or just slow, are worth less then they were a few months ago.

Many owners will try to kick the can down the road. “I’ll spend a few years building the business back up, then I’ll sell it.” For some, that was their plan after the recession. Unless you have something new up your sleeve, you may be waiting a long time for the right buyer to come along. In the next economic cycle, you may wait too long. You can only kick that can so far.

If you are a Baby Boomer, the time to be planning your exit is now. That goes double if you are sitting in your house wondering what comes next. Most entrepreneurs started a business because they wanted control over their lives. When there’s an event that takes away that control, your best response is to get it back.

Exit Planning in a Crisis

Your exit plan starts with some basic questions.

  1. Do I know how much I need to retire, with a professional analysis of my living expenses, life expectancy and inflation assumptions?
  2. Do I know how much my company is really worth, and who is most likely to pay me that amount?
  3. If #2 doesn’t meet the needs of #1, do I know how long, and what it would take, to get my business there?
  4. Do I know all the options for monetizing my business, including a sale to employees, another entrepreneur or professional acquirers?

If you are a Baby Boomer, unless you are exit planning in a crisis, you risk a discussion in 2025, or 2028, or 2031 that starts with “Well. the coronavirus hit our industry pretty hard, you know.”

There is a network of advisors in the USA and Canada who specialize in a reasonably priced, 90-day planning process for small business owners, and who use a suite of online tools to help you work through all these questions remotely. They can help get you started right now.

For a listing of these advisors, go here.

John F. Dini, CExP, CEPA is an exit planning coach and the President of MPN Incorporated in San Antonio Texas. He is the publisher of Awake at 2 o’clock, and has authored three books on business ownership.

Quarterbacking is Not Exit Planning

Quarterbacking is a popular term when exit planners are talking to clients. It’s supposed to invoke a vision of someone who is in control. Think about a Tom Brady, Aaron Rodgers or Patrick Mahomes standing tall in the pocket, surveying the offense and defense unfolding before him.

There is a real problem with using “Quarterbacking” when referring to your exit planning professional team. The quarterback calls the plays. The job of the rest of the team is to run them as instructed.  I’ve yet to meet a CPA or attorney who thinks that is the best way to develop a client’s exit plan.

Teamwork

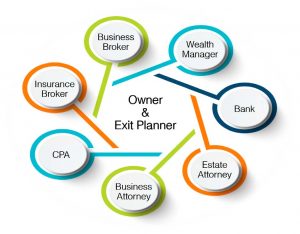
Exit planning, like no other form of professional consulting, is a team sport. When I am engaged by a client, I have the responsibility of defending his or her long-term objectives. The other advisors, who may include an insurance agent, financial planner, or appraiser, all have experience to lend to the process.

We can modify a plan multiple times and in many ways. The accountant may have some excellent restructuring ideas to save taxes. The attorney can add terms to a buy/sell agreement to protect the owners from having their equity unfairly valued by the IRS, or from having it pass to parties outside the company.

The insurance agent can mitigate the risk of illness or death derailing the timely transfer of the business, or of the surviving family being left destitute. The appraiser can develop valuations that take advantage of the discounts permitted under IRS guidelines.

Each of these professionals has a role, and should be able to add their skills to the process, with only one exception. They should not be permitted to do anything that interferes with the owner’s objectives. That’s the responsibility of the exit planner.

The Alternative to Quarterbacking

I prefer to think of the exit planner’s role as analogous to that of an orchestra conductor.

quarterbackingThe exit planner may not be as skilled in any specific discipline as the others on the team. He may know something about tax planning, or legal structuring or insurance. She probably knows a bit about valuation and even more about contracts.

But, like the conductor, he or she doesn’t know more about any of those subjects than the advisor who spends full-time in that area.

No one expects the conductor to step off the podium for a violin solo, or to fill in for the French Horn.  In fact, you don’t even want the conductor to tap the triangle for that one little note in the pause. If he did, he would be distracted from his primary role of keeping all the musicians on the same page.

Having one advisor coordinate the contributions of others greatly improves the overall result. Expecting him or her to dictate details outside his area of expertise is foolish. Expect your exit planner to lead without quarterbacking.

John F. Dini, CExP, CEPA is an exit planning coach and the President of MPN Incorporated in San Antonio Texas. He is the publisher of Awake at 2 o’clock, and has authored three books on business ownership.