Exit Planning Tools for Business Owners

Life After Exit — Time is of the Essence

From time to time, we share real stories about life after exit from owners who have sold their businesses. Some are great and some… not so much. The have agreed to share their experiences to help other owners prepare for both the process of transferring their companies and what comes after.

The Business

BVA Scientific, a distributor of laboratory supplies and equipment, started in Bob and Nancy Davison’s bedroom with the garage serving as the “warehouse.” Both had a background in laboratory supply sales, and they focused on building deeper customer relationships than the multi-billion dollar vendors who dominate the industry.
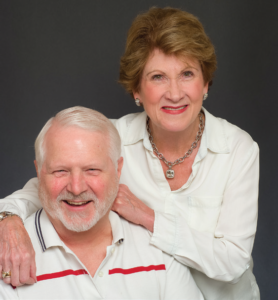
That approach helped the company grow with a balanced customer base. BVA has a presence in food testing laboratories, water and wastewater plants and the Texas oil fields, rather than the typical dominance of doctors and hospitals for their type of business.

Not surprisingly, BVA had attracted multiple inquiries from private equity groups. None of those came with management, however, and all wanted the Davisons to remain as employees for a long time after the acquisition. While they weren’t in a rush to get out the door, Bob and Nancy wanted a clear path to retirement

Here is how they describe the transaction

“First, let’s kill all the lawyers…”

Nancy: “We knew that the business had grown beyond what a couple of salespeople could handle well. Supply sources were moving to Asia, and I felt a bit out of step. I think the real impetus was when a general manager to whom we planned to sell the business left for, of all things, his own sign shop franchise. We hired a replacement, but we could see that he wasn’t our exit plan.”

Bob: “I’ve always been very active in our trade association. A colleague with a much larger operation had asked me several times to let him know if we would consider selling. When he repeated the offer at a conference, we decided to start talking seriously.”

Nancy: “The due diligence almost killed me. The buyer’s attorneys kept asking for more information. Halfway through the deal their lead attorney went on maternity leave, and her replacement wanted to restart the whole process from the beginning!”

Bob: “Our legal bills wound up being so much more than we anticipated. I think my biggest surprise was finding out how many adjectives could be used to modify the word lawyers.”

Nancy: “The closing date was delayed multiple times. Then our biggest customer told us privately that they were planning to shift their purchasing for high-volume items to China. It was a gut check, but we shared the information with the buyer. We had to restructure the deal with a portion tied to an earn-out, based on the level of business we maintained for a year after closing.”

Life After Exit

Bob: “Nancy stepped back pretty quickly. I wasn’t quite ready to retire, and now I have the added motivation of watching our earn-out. My role is technically sales-related, but it is just as much about keeping the employees happy through the change.”

(Note: As we approach the end of the earn-out agreement, BVA Scientific has easily reached all the goals required for full contingency payment. Nancy and Bob continue to enjoy life after exit.)


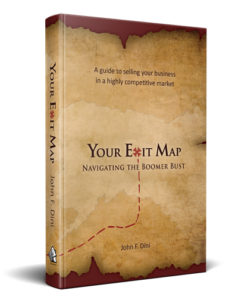
This story and others are in my latest book Your Exit Map: Navigating the Boomer Bust.
Exit Planning – Maintaining Control

For many owners, their biggest concern in an exit plan is maintaining control.  Whether they seek to sell to employees, family or a third-party, there is a fear that, once started, the process will have its own rules and momentum.
My colleague John Warrillow, author of Built to Sell and The Automatic Customer, has written an excellent white paper on the types of people who own businesses. John previously owned a data-driven marketing company, and always backs up his opinions with solid research.

I’ll leave the indicators of the entrepreneurial types to John, since it is his material. His conclusion, however, is that 2% of owners are Mountain Climbers. They are focused entirely on the next goal (usually growing the business.) Another 24% are Freedom Fighters; those who are in business for themselves as a way to control their lives. The remaining 74% are Craftspeople. They run their own business as a job, focusing on doing much of the work themselves to maintain the best quality.

Craftspeople aren’t prime candidates for exit planning. Their owner-centric approach to the business leaves them little value to sell to another entrepreneur. Mountain Climbers are almost certainly planning an exit, but their objective is probably to reach a level that attracts financial and strategic acquirers.

That leaves Freedom Fighters as about 92% of the owners who will benefit from a planned transition. Maintaining control is their very reason for owning a business. They have no intention of surrendering the outcome to someone else.

Sharing Control with a Buyer

Ironically, the majority of these owners say that they plan to sell their companies to a third party. By definition, they will be sharing the timing, price and transfer mechanisms with a stranger. The buyer will have his or her own ideas about the process and how much the company is worth.

Combining Warrillow’s  work with my own research on the number of Boomer employers (5 or more employees) in the U.S., and we can estimate that somewhere between 750,000 and 1,500,000 of these businesses are owned by Freedom Fighters over 55 years old. If you’ve read my latest book or visit this column regularly, you already know that the intermediary community (brokers and investment bankers), accounts for about 10,000 third-party sales annually.

These owners don’t have a century or more to stand on line waiting for a buyer. That’s why so many are choosing to sell their businesses to employees.

“But my employees have no money!” That first objection is usually true, but if they have the skills to run the business, the financial mechanisms can often be arranged. A Leveraged Buyout (LBO) or an Employee Stock Ownership Plan (ESOP) can be structured over a few years so that the owner remains in control of the business until he or she leaves with the full value of the company in his or her pocket.

Of course, you can always finance the transaction yourself, and sell to employees for a note. That, however, is the antithesis of maintaining control.


Choosing Your Timeframe to Exit

“My timeframe? Talk to me in about five years.”

When business owners are asked about exit planning, that answer is almost ubiquitous. In fact, a much-quoted 2008 survey of owners by Price Waterhouse Coopers (now PwC – not clear why Mr. Waterhouse warranted lower case) found that 85% of private business owners said they expected to sell in five years.

Clearly, that didn’t happen, since it would have required some  1,500 businesses to be sold daily during that period. (The brokerage industry claims about 9,000 sales a year.)

In fact, when the survey results were broken down, they discovered that 85% of 60 year old owners expected to sell in five years. Among 65 year olds, 85% expected to sell in five years. Among 70 year olds, you guessed it, 85% expected to sell in five years.
Clearly, “five years” is most owners’ shorthand for “I haven’t really thought about it.”

Realistic Timeframes

Exit planning and more importantly, implementing a plan, can easily take five years. That doesn’t include the time thinking about it, talking about it, or waiting for someone to call you up and make an offer.

If you are an owner-centric business (for example, a specialty craft where either you do the work or it is all done under your personal supervision,) you exit plan may be to close down. Even so, respect for your customers and employees suggests that discontinuing the business should take about a year.

Main Street businesses are those where another individual could step into your shoes and make a living. Such companies generally sell for less than $2 million. This is the market where business brokers excel. Expect the listing and sale process to take anywhere from nine months to two years. That is after you’ve done any needed clean-up of your records, contracts and procedure documentation.

If you plan to sell to employees without taking on all of the financing risk personally, allow at least three years to bring them into an equity position and document their ability to run the business without you. For most companies, five to eight years is a more realistic timeframe to accomplish this.

Selling to family members who are already capable of running the business is also time sensitive. A family transition can offer unique tax benefits, but the transfer mechanisms usually need at least five years for maximum benefit.

Selling to a family member who is not yet involved in the business is a much more lengthy proposition. I meet regularly with owners in their 60s who claim that a son or daughter in high school will be their successor. That timeframe requires the owner’s presence until well into his or her 70s or beyond.

Planning Isn’t Implementing

It makes little sense to embark on the biggest financial event of a lifetime without planning. However, plans can be made without rushing right into them.

Too many owners start to plan, only to find that the assumptions they’ve held for years aren’t true. Their estimate of value for the business is way off, or the key employee they assumed would take over has little interest in ownership.

Testing a plan for its practicality helps focus you in a specific direction. Does the business need to grow, improve profitability or take on new lines? Who are the buyers for a business of your size, or in your industry?

Investments in new hires and equipment are weighed for their long-term impact more than immediate need. Even if your target date is a decade away, you’ll start making strategic and tactical decisions based on your ultimate goal.

“Read” my latest book in 12 minutes!

Your Exit Map, Navigating the Boomer Bust is now available on Amazon, Barnes & Noble and wherever books are sold. It was ranked the #1 new release in its category on Amazon, and is supplemented by free tools and educational materials at www.YourExitMap.com.

Now, we have a really cool 12 minute animated video from our friends at readitfor.me that summarizes the book, and helps you understand why it is so different from “how to” exit planning tomes. Take some time to check it out here. Thanks!


Internal Transfers: Legacy vs. Lucre

Lifestyle vs. Legacy

Why would I refer to the results of an internal transfer as “lifestyle vs. lucre?” Lucre is a pejorative term. While it is technically just a synonym for money, most dictionaries draw the parallel to its use in “filthy lucre;” money that is ill-gotten or otherwise dishonorably obtained.

I was honored to present at the Exit Planning Summit this past weekend. One of the things I discussed was the need to help business owners determine whether their personal vision for their company’s future was based on lifestyle or legacy. That’s how I normally term it, and there is no negative connotation attached to either term.

That “lifestyle vs. legacy” decision, however, usually designates the difference between selling to a third party for full market value (lifestyle) and selling to employees in order to preserve the culture and quality of the organization (legacy.)

Legacy vs. Lucre

“Legacy vs. lucre” is my term for the differing motivations in an internal transfer, and it is fully intended to be pejorative.

For a business owner, the greatest appeal of an internal transfer is control. He or she gets to pick the new owners, their timeframe for taking over the company, and how much they will have to pay.

Sometimes, that avenue to exit is chosen because the owner knows he or she can’t get a satisfactory price in the open market. The company just isn’t worth what he wants for it.

So selling to employees becomes a vehicle to get more than fair market value. Of course, no third-party lender will touch a deal for more than the business is worth, so almost by definition such transactions have to be seller-financed.

That is one of the reasons we hear horror stories about selling a business to employees for a note, and having to take it back when they default. Their failure may have been due to a lack of training to run the business, or an unsupportable price. Either way, they were set up for failure by an owner who was more interested in getting a check than in what happened down the road.

Legacy Requires Win-Win

Selling to a third party is an arms-length transaction. Both parties have their own agenda and advisor team. The buyer is perfectly cognizant of Caveat Emptor. The seller wishes to maximize the proceeds, the buyer to minimize his cost. The result is usually something in between.

When selling to employees, the playing field isn’t even. The employees have followed the seller’s direction for a long time. They are accustomed to doing what he says. It’s when the owner takes unfair advantage of his status that legacy turns into lucre.


“Read” my new book in 12 minutes!

Your Exit Map, Navigating the Boomer Bust is now available on Amazon, Barnes & Noble and wherever books are sold. It was ranked the #1 new release in its category on Amazon, and is supplemented by free tools and educational materials at www.YourExitMap.com.

Now, we have a really cool 12 minute animated video from our friends at readitfor.me that summarizes the book, and helps you understand why it is so different from “how to” exit planning tomes. Take some time to check it out here. Thanks!

After the Exit; “Nothing Will Change”

“Nothing will change.” It is almost de rigueur for an acquirer to include that in his or her opening comments to the incumbent staff of a just-purchased business. Sometimes it is the seller’s attempt at making folks feel better. “Don’t worry. They promised me that nothing will change.”

In the moment, it seems like a calming thing to say, a confidence builder for the employees who have just been informed that they have a new boss. In the long run, it can cause more problems than it solves.

Everything Changes

In any company, change is ongoing. Employees are asked to learn additional skills. Systems are upgraded. Procedures are rewritten. People are promoted or terminated. Customers leave, or (hopefully) big new accounts with new requirements are landed.

No experienced business owner in his or her right mind would ever promise employees that “Nothing will change.” Change is part of the landscape, and adjusting to it is inherent in keeping the business growing and relevant. Employees accept that fact unconsciously, because it’s always been part of the landscape.

Of course, when an acquirer says “Nothing will change,” he means today. There will be new procedures. New reporting relationships will have to be worked through. Software will be modified, or even discarded for the acquiring company’s preferred systems. And eventually, some employees will be promoted or terminated based on their ability to accommodate those inevitable changes.

“Nothing will change” is a license for employee dissatisfaction. They have to learn a new telephone system. (“He lied. This is a big change.”) All invoicing will be done through the central office. (“She lied. This is a massive change.”) Job descriptions and incentives will be adjusted to match the parent company’s. (“He lied. Everything is changing!”)

Demystify Change

The appropriate soother for acquisition anxiety is the truth. “I know this is a big change. You’ve faced great changes in this company before (get some examples from the seller) and your ability to adjust and succeed is what makes us so excited to be teaming up. We’ll take things slowly to start, and work with you so that our integration will be as painless as possible.”

There are no magic words that can completely eliminate employee concern. Dealing with it by promising something that isn’t true is just incurring a long-term cost for a very short-term benefit.