Exit Planning Tools for Business Owners

Exiting a Family Business: Three Questions

Transitioning a Family Business has special issues. This interview was reprinted last week in the newsletter of Steven Bankler, CPA.

We asked San Antonio business consultant John F. Dini, one of the nation’s leading experts on business ownership and exit planning, for his advice on handing down the family business. As the author of Hunting in a Farmer’s World, Beating the Boomer Bust and 11 Things You Absolutely Need to Know About Selling Your Business, Dini literally “wrote the book” on succession planning. He recommends that Baby Boomers and other business owners with an eye on retirement carefully consider the following questions.

What will your role in the company be?
Dini says that many owners “hand off” their companies without a real succession plan, especially when the business is destined to stay in the family. In those cases, ownership is often passed on while control remains—officially or unofficially—in the hands of the original owner, which can cause significant problems.

“Discuss what you want your level of activity to be, and what your successors think it should be,” he advises.  “Keeping your old office, or showing up every day to ‘just check on things,’ cripples your successor’s authority and ability to implement his or her own vision for the business.”

Is your successor ready, willing and able to handle change?

Many second-generation owners are indoctrinated to run the business exactly as they were taught.  However, as Dini points out, that may not be the best course of action.

“Markets, products and technology evolve,” he says, recommending that you consider: “Is your successor ready to adjust to changes in the business? Does he or she have any experience in dealing with major disruptions, such as the loss of a key customer or employee?”

Also understand that you cannot replicate your own mix of skills and talents in a successor, especially when it comes to the experience and “battle scars” you’ve gained along your entrepreneurial journey.

“It’s often impossible to train a successor as a ‘utility infielder’ who can handle finance, operations and sales,” Dini explains. “If key employees are critical to supplement certain areas of running the business, they should be included in a family business succession plan with long-term incentives for retention.”

Does the company have the financial strength to thrive without your personal signature?

“As a family business expands, an owner’s ability to personally guaranty its liabilities usually grows with it,” cautions Dini. He recommends taking an honest, comprehensive look at how your departure will affect finances from both the business and personal sides.

“Can the company maintain necessary credit facilities if you don’t back them up? If not, consider talking to your bank about how to limit your exposure,” he advises. “Many parents have lost their savings because they stopped watching the business until the calls started coming from its creditors.”

Succession in family businesses is often a balancing act between the desire to give the children appropriate freedom to run the company and protecting the assets of the parents. Planning should encompass timing, authority and financial responsibility, with all parties agreeing on the parameters.

Do you know the owner of a family business? Please share!
Exiting a “Time and Place” Business

“The purpose of middlemen in the marketplace is to provide time and place utility.” I remember the light bulb going on in Economics 101 when my professor said that.  Suddenly, I understood the concept of added value. Someone had to get the product to the customer.

“After all,” the professor continued, “The footwear manufacturer in Massachusetts can’t sell a pair of shoes directly to someone in California. They can’t manufacture and handle thousands of customers. It would be a nightmare, and completely unprofitable.”

The fact that Massachusetts was still known for shoe manufacturing gives you some idea of how long ago this took place. So long ago, in fact, that Zappos wasn’t even a word yet.

The independent shoe retailer gave way to the department stores. In turn their shoe business was decimated by the specialty chain retailers. In fact, most shoe departments in Macy’s and others are actually chain operations within the store. Shoe sales moved into sporting goods stores and discounters. While the industry shifted multiple times, they all still provided time and place utility.

Then came the Internet. Now the manufacturer can sell directly to consumers. In fact, they can eliminate several layers of middlemen, along with the mark-ups.

Lately my area has been swamped with billboards saying “Mattress Dealers are Greedy. TN.com.” TN.com turns out to be Tuft and Needle, a direct selling (via Internet) manufacturer of mattresses. Their pitch is based on eliminating the middlemen. They have diagrams for their supply chain (From us to you.) on the website, along with a list of the markups in the “other guys” logistic chains.

Providing time and place convenience to consumers is challenging when your competitor’s time offering is 24 x 7 x 365 and the place where they purchase is their own home. Even when you need something “right away” online vendors will deliver in as little as two hours.

Last December my wife went out early on a Sunday morning to, “Pick up a few last gifts in time to ship them.” She returned an hour later, empty-handed. “This is ridiculous,” she said. “I’m going to finish my shopping on the Internet, and have all the gifts shipped for me.”

There’s an additional issue when it comes to selling time and place businesses. Many of the new generation of business buyers, the Millennials, value their personal freedom above financial opportunity. They have little interest in coming in early to open up, or staying late to close. Skipping the Thanksgiving family dinner to prep the store for Black Friday is a non-starter.

If you are hoping that I will reveal the secret sauce for perpetuating a time and place business, I’m afraid I’ll disappoint you. There is no magic formula aside from the age-old wisdom of differentiation and service.

Beating Time and Place

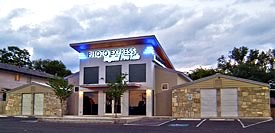
My friends at Digital Pro Lab in San Antonio are an excellent example of adjusting to change. What could be more outdated than a drive-up 30 minute film developing shop? What was formerly an epitome of time and place convenience (pictures in a half hour without getting out of your car), has become almost a caricature of “old school.”

Technology has shifted from celluloid film to digital. “Developing” now consists of uploading the files from your phone to a mega-printer who mails 8×10 prints overnight for less than Digital Pro’s cost. The photo chains, Ritz Camera, Fox Photo, and Wolf Photo are all gone, crushed by those “mail order, ” or perhaps more properly “email order” houses.

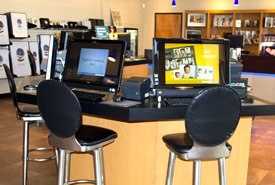
Digital Pro has survived (and thrives) by their differentiation and service. The large, bright showroom is full of computers where they can show customers the effect of adjusting color balance or editing. They can print your lifetime memories on almost anything, from a key chain to a large metal panel. They can still give you prints made with permanent liquid ink, not the water soluble powder used by most printers.
In addition, they can do all of this online because they’ve invested in the technology necessary to keep up with the “convenience-based” competitors.

As the cost of digital printers fell, professional photographers invested in their own machines. Digital Pro Lab has replaced their business with consumers who want to discuss their special moments, choose how to preserve them, and hold the results in their hands before they pay.

In an industry where the number of time and place based outlets has fallen by over 90% in the last decade, Digital Pro Lab has beaten the big boys with product differentiation and service. When the time comes for planning an exit, they will have options.

Do you know a business owner who will be exiting in the next ten years? Please share Awake at 2 o’clock!

Exit Planning: Telling Secrets

Planning your exit from a business is a process of telling secrets. For many owners, it is the most terrifying part of selling.

A rancher in South Texas once said to me, “I’m going to tell you a secret, and you have to solemnly swear not to tell anyone. When you do, you have to make them swear the same thing.”

Most business owners are very cautious about with whom they share their exit plans. The logic is intuitive. The more the information is shared, the bigger the chance is that someone will use the knowledge against you.

telling-secretsCompetitors will tell customers, insinuating that your company will no longer be a dependable supplier. Employees might begin looking for greater security in other jobs. Vendors may seek another distribution channel. Your bank could start tightening your credit.
Yet your buyer wants to verify due diligence information. He wants to talk to key employees and customers. Lines of supply and the solidity of relationships have to be confirmed.

Some owners are unduly afraid of letting anyone know their plans. Sooner or later everyone will know, but when they should be informed is an important part of your planning. Controlling the distribution of information might have dramatic impact on the value of your business.

Those who should know about your plans can be placed in three groups.

Round One

Key employees: Whether they are slated to be the next generation of owners or not, key employees should be the earliest group informed of your plans. Of course if you are contemplating an internal sale, their willingness and ability to buy the company requires disclosure. If you are planning an external sale, their cooperation in preparing the company for a buyer’s due diligence will be critical.

Consider having the employees sign a new non-disclosure agreement. Even if you have confidentiality provisions in your employment contracts or policy manual, it serves to emphasize the sensitive nature of exit planning information.

Round Two

Going outside your trusted inner circle is a big step, but you should consider it once you have a solid buyer in place. Sharing earlier, rather than later, makes due diligence easier.

General Employees: Employees can usually be informed fairly early in the sale process. Explain that the transition of the company is a normal part of its lifecycle, and that you are taking steps to ensure that it is done with an eye to their continued  employment. That will go a long way to making them feel more secure. If you treat it like a dark secret, they will have greater concerns about the inevitable rumors.

That’s why I suggest you inform the employees before you tell vendors and competitors, from whom they are likely to hear it anyway. Bringing them “in the know” will also help forestall any hiring attempts by other businesses. Inertia is a powerful force. Usually after a few weeks with no major disruption, the employees just accept your exit planning as a fact of life.

Critical vendors. If you have an exclusive distribution or supply relationship with some larger companies you may already be fielding requests for a documented succession plan. Many suppliers appreciate the forethought of exit planning because it ensures the stability of their distribution chain.

One area of caution. Watch out for a vendor’s loose lipped salespeople, who may regard news of your pending departure as hot gossip for the rest of their customers.

Round Three

Customers: Most customers should be told as late as possible before the transaction closes. If informed of a fait accompli, they are likely to stick with the relationship long enough to gain some experience with the new owners. If informed too far in advance, customers will logically begin to look for alternative sources of supply.

Lenders: While many bankers and other lenders will say that they ought to be informed as early as possible in the process, it is often not a great idea. They may seek the opportunity to finance a transaction, and certainly would like to begin a relationship with any new owner as soon as possible, but they also have a primary responsibility to protect the assets of their institution.

That means they have to worry about the security of your personal guarantees, and whether they see any risk to their capital in your business. Discussions with your bank should include details about the future of your banking relationship.

Due diligence is only one step in the process of telling secrets. Lots of other stakeholders will need to be informed. How and when you do that should be a formal part of your planning process.

yem-flat-cover-smallThank you for reading. If you would like to receive free, pre-publication excerpts of my next book, please register here.

The Immortal Business Goes on Forever

Do you run an immortal business? I hope so. If you answered “no,” or even hesitated to be sure of your response, then you don’t think of your business as immortal.

So when do you plan to shut it down?

Most owners react viscerally to that question. They’ve invested too much time and too much sweat to watch their companies become a memory. They care too much about employees and customers to entertain the idea of  abandoning them.

ForeverFor many, the business is a part of them. Shutting it down would be like having a piece of you die.
Ironically, we play mental gymnastics in our heads every day. We think we have an immortal business. We know we aren’t immortal (on this plane of existence, at least.) Yet, I talk to owners every day who want to pretend that either they will run the business forever, or that it will find some magic way to continue without them.

Anyone who works in exit planning knows the standard answers to the question “What is your exit plan?”

  • “I intend to look for a buyer in about 5 years.”
  • “I still enjoy my business. Talk to me after I get tired of it.”
  • “I’ll sell anything for the right price if someone offers it.”

Each of those answers is a version of “I haven’t thought much about it, and I really don’t want to.” I wouldn’t be much of a consultant (or at least I’d be an impoverished one), if I didn’t have some counter arguments ready.

  • “I intend to look for a buyer in about 5 years.” That’s fine, but five years is about the minimum time you should allow for any serious tax planning. If you are going to take a subchapter S election, create a new entity, or change your  depreciation methods, it will take some time to have the desired effect. Of course, the Internal Revenue Service already has a plan for how they would handle the proceeds, so you could just go with theirs.
  • “I still enjoy my business. Talk to me after I get tired of it.” That is clearly too late. Whether you are selling to employees or family, or marketing the company to third parties,  the business needs to be running well to survive a transition to new ownership. Once you start losing interest, it gets much tougher.
  • “I’ll sell anything for the right price if someone offers it.” Sure but what is the “right” price? Is it based on industry metrics? Is it some multiple that a guy from a vendor told you a competitor sold for? Is it a number you need for retirement that has little to do with market value? If you received an offer tomorrow, how would you know if it was the best offer you might ever see?

The most important thing to remember is this: Planning is only planning. Implementation is a different activity in the management cycle. Just because you have a plan doesn’t mean you will use it today or tomorrow, but it will still be there when you choose to put it into action.

If you own an immortal business, you have an obligation to the folks who depend on it. Part of that is to know how they will be able to continue depending on it when you aren’t there.

If you know a business owner who would benefit from “Awake at 2 o’clock,” please share!

still

Selling Your Business: Money isn’t Everything

When I was a kid my mother said “Money isn’t everything” in response to every envious glance at another kid’s stuff. As I became successful enough to afford things for my children, I reversed the meaning. “Money isn’t everything” became my reminder that their possessions didn’t make them better or happier than others.

The same holds true for companies. An entrepreneur who is struggling to generate sufficient working capital is an unlikely prospect for a lender, let alone an investor.

I regularly receive approaches from business owners who have a great ideas, but have run out of capital without generating cash flow.  They usually have trouble understanding why I don’t want to represent them in their investment search (for a fee contingent on only my success, of course.)

“But everyone says there is plenty of money looking for deals,” they say. It is true. There is always more money available than good investments. That’s why so many investments lose money.

Once your business approaches $1 million in annual earnings, the whole capital landscape changes dramatically. If you are scalable (meaning you likely have around 100 employees or more) your deal is attractive to financial investors such as private equity groups. There are currently about 7,000 such buyers in the US, pursuing the 17,000 or so companies who meet their criteria.

These buyers range from Search Groups (who have investors lined up if they find a company), to investment funds with a billion dollars or more in “dry powder” (cash in the bank).

If you are smart, and clever, and tenacious, and lucky, you can reach the point where there is plenty of money to buy you out. In fact, money is probably chasing you. Most sellers, however, come to realize that money isn’t everything.

shark with dollarThe M&A world abounds with horror stories of financial buyers who stripped the employee benefits from a company and drove off its key personnel. Others pulled their capital as soon as they had control (to leverage it in another deal) and left the business staggering under the debt replacing it. Still more inserted a Hired Gun executive from another industry whose inexperience quickly ran the business on the rocks.

That might not be your concern if you walk away with a terrific multiple, but if the deal (like many) requires you to leave a substantial amount on the table for a few years, it’s critical.

I work with business owners in their exit planning. Although I haven’t brokered in years (meaning list and market businesses for sale), I regularly advise owners who are dealing with an approach from financial buyers. Here’s my mental checklist for vetting a financial buyer:

  1. Do you trust them? Can you see working side by side with them as your partners?
  2. Do they understand your business and your customers, or are they just looking at your financial statements?
  3. How important to you is the future of your employees and your reputation?

Notice that the questions don’t include “How much money do they have?” If you are attractive to one financial buyer, you are probably attractive to a lot more.

Many of my clients, when they examine the non-financial aspects of selling, choose alternative exits. They arrange for the employees to buy the business, or merge with a friendly competitor. They may not make quite as much, but money isn’t everything.

If you enjoy Awake at 2 o’clock and know a business owner who would benefit from reading it, please share. Thanks!