Exit Planning Tools for Business Owners

Life After Exit — Time is of the Essence

From time to time, we share real stories about life after exit from owners who have sold their businesses. Some are great and some… not so much. The have agreed to share their experiences to help other owners prepare for both the process of transferring their companies and what comes after.

The Business

BVA Scientific, a distributor of laboratory supplies and equipment, started in Bob and Nancy Davison’s bedroom with the garage serving as the “warehouse.” Both had a background in laboratory supply sales, and they focused on building deeper customer relationships than the multi-billion dollar vendors who dominate the industry.
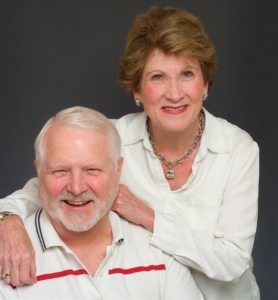
That approach helped the company grow with a balanced customer base. BVA has a presence in food testing laboratories, water and wastewater plants and the Texas oil fields, rather than the typical dominance of doctors and hospitals for their type of business.

Not surprisingly, BVA had attracted multiple inquiries from private equity groups. None of those came with management, however, and all wanted the Davisons to remain as employees for a long time after the acquisition. While they weren’t in a rush to get out the door, Bob and Nancy wanted a clear path to retirement

Here is how they describe the transaction

“First, let’s kill all the lawyers…”

Nancy: “We knew that the business had grown beyond what a couple of salespeople could handle well. Supply sources were moving to Asia, and I felt a bit out of step. I think the real impetus was when a general manager to whom we planned to sell the business left for, of all things, his own sign shop franchise. We hired a replacement, but we could see that he wasn’t our exit plan.”

Bob: “I’ve always been very active in our trade association. A colleague with a much larger operation had asked me several times to let him know if we would consider selling. When he repeated the offer at a conference, we decided to start talking seriously.”

Nancy: “The due diligence almost killed me. The buyer’s attorneys kept asking for more information. Halfway through the deal their lead attorney went on maternity leave, and her replacement wanted to restart the whole process from the beginning!”

Bob: “Our legal bills wound up being so much more than we anticipated. I think my biggest surprise was finding out how many adjectives could be used to modify the word lawyers.”

Nancy: “The closing date was delayed multiple times. Then our biggest customer told us privately that they were planning to shift their purchasing for high-volume items to China. It was a gut check, but we shared the information with the buyer. We had to restructure the deal with a portion tied to an earn-out, based on the level of business we maintained for a year after closing.”

Life After Exit

Bob: “Nancy stepped back pretty quickly. I wasn’t quite ready to retire, and now I have the added motivation of watching our earn-out. My role is technically sales-related, but it is just as much about keeping the employees happy through the change.”

(Note: As we approach the end of the earn-out agreement, BVA Scientific has easily reached all the goals required for full contingency payment. Nancy and Bob continue to enjoy life after exit.)


This story and others are in my latest book Your Exit Map: Navigating the Boomer Bust.
Exit Planning – Maintaining Control

For many owners, their biggest concern in an exit plan is maintaining control.  Whether they seek to sell to employees, family or a third-party, there is a fear that, once started, the process will have its own rules and momentum.
My colleague John Warrillow, author of Built to Sell and The Automatic Customer, has written an excellent white paper on the types of people who own businesses. John previously owned a data-driven marketing company, and always backs up his opinions with solid research.

I’ll leave the indicators of the entrepreneurial types to John, since it is his material. His conclusion, however, is that 2% of owners are Mountain Climbers. They are focused entirely on the next goal (usually growing the business.) Another 24% are Freedom Fighters; those who are in business for themselves as a way to control their lives. The remaining 74% are Craftspeople. They run their own business as a job, focusing on doing much of the work themselves to maintain the best quality.

Craftspeople aren’t prime candidates for exit planning. Their owner-centric approach to the business leaves them little value to sell to another entrepreneur. Mountain Climbers are almost certainly planning an exit, but their objective is probably to reach a level that attracts financial and strategic acquirers.

That leaves Freedom Fighters as about 92% of the owners who will benefit from a planned transition. Maintaining control is their very reason for owning a business. They have no intention of surrendering the outcome to someone else.

Sharing Control with a Buyer

Ironically, the majority of these owners say that they plan to sell their companies to a third party. By definition, they will be sharing the timing, price and transfer mechanisms with a stranger. The buyer will have his or her own ideas about the process and how much the company is worth.

Combining Warrillow’s  work with my own research on the number of Boomer employers (5 or more employees) in the U.S., and we can estimate that somewhere between 750,000 and 1,500,000 of these businesses are owned by Freedom Fighters over 55 years old. If you’ve read my latest book or visit this column regularly, you already know that the intermediary community (brokers and investment bankers), accounts for about 10,000 third-party sales annually.

These owners don’t have a century or more to stand on line waiting for a buyer. That’s why so many are choosing to sell their businesses to employees.

“But my employees have no money!” That first objection is usually true, but if they have the skills to run the business, the financial mechanisms can often be arranged. A Leveraged Buyout (LBO) or an Employee Stock Ownership Plan (ESOP) can be structured over a few years so that the owner remains in control of the business until he or she leaves with the full value of the company in his or her pocket.

Of course, you can always finance the transaction yourself, and sell to employees for a note. That, however, is the antithesis of maintaining control.


The Right Price for Your Business

“If someone offered me the right price, I’d sell in a minute!” Exit planners and business brokers hear it all the time. “Anything is for sale if the price is right!”

What is the “right” price? Of course, you can fantasize about a windfall from a buyer who has far more money than brains. Some of the fast-talking “business brokers” (the ones who get more revenue from preparing offering books than actually selling companies), will pitch their secret list of buyers in Europe and Asia who routinely overpay for businesses.

In case you didn’t know, the largest advisory firms in Europe and Asia are the same ones we have here. The same accountants, the same attorneys, the same investment bankers and the same consultants. It’s unlikely that they give their wealthy overseas clients lesser quality advice than the ones in North America.

Barring purchase by a lunatic, your business is likely to be priced around Fair Market Value; the arms-length amount that an independent buyer will pay an independent seller.

Beauty is in the Eye of the Beholder

You are the seller, and your company is what it is. Buyers, however, come in a variety of sizes and flavors. Understanding why companies have different values to differing buyers is critical if you plan to maximize your proceeds.

Here is a 2 1/2 -minute video on valuation from our website of free tools for business owners at www.YourExitMap.com.

These are the typical ranges for “fair market value.”

If you are earning less than $500,000 in total salary, profits and benefits from the business, your likely price is between 2.5 and 3.5 times the SDE (Seller’s Discretionary Earnings.) These are “Main Street” businesses; typically sold to individuals.

Once you exceed $1,000,000 in Earnings before Interest, Taxes, Depreciation and Amortization, or EBITDA (but not counting your personal salary and benefits) you are a target for professional investors. These include private equity groups and family offices. In this market, valuations between 4 and 6 times earnings are common. If your EBITDA is over $2,000,000 it could be substantially higher.

Strategic and industry buyers (who may be the same) could pay more, but those transactions are very specific to the situation. In simple terms, the right price is whatever you can get. If the acquirer has a plan to plug your business into an existing customer base and grow it substantially, earnings often become a secondary issue.

The Neutral Zone

The “neutral zone” contains those companies who earn more than $500,000 (SDE) but generate less than $1,000,000 EBITDA. This is a fairly broad range.

Let’s use an illustration. An owner takes a $400,000 salary along with another $250,000 in benefits, and shows a pre-tax profit of $700,000. Clearly that is a healthy small business. In the “Main Street” market the company could value at between $4 and $5 million.

An individual buyer would need at least 25% down ($1,000,000 cash) plus working capital, and be able to guarantee loan payments of about $500,000 a year. That’s well beyond the range of most individuals.

Yet unless this business has a unique product or intellectual property, it is likely of no interest to professional, industry or strategic buyers.

Many of these companies are choosing a staged sale to their management teams. Others choose to kick growth into a higher gear in order to reach the next stratum of buyers and valuation. Either approach will usually take at least five years.

Controlling the Right Price

Some owners are choosing both approaches. They use ownership as a management incentive to achieve growth targets. If the company makes the leap into a buyer market with higher valuations, both the owner and the management team win.

If the company doesn’t attract the target buyers, the owner still has a solid exit strategy from a more valuable company. Getting the right price requires the right plan.

“Read” my new book in 12 minutes!

Your Exit Map, Navigating the Boomer Bust is now available on Amazon, Barnes & Noble and wherever books are sold. It was ranked the #1 new release in its category on Amazon, and is supplemented by free tools and educational materials at www.YourExitMap.com.

Now, we have a really cool 12 minute animated video from our friends at readitfor.me that summarizes the book, and helps you understand why it is so different from “how to” exit planning tomes. Take some time to check it out here. Thanks!

Why GenXers Won’t Buy Your Business

There are six reasons why GenXers won’t buy your business.

Last week I presented a webinar for the Exit Planning Institute entitled “The Perfect Storm.” It looks at six factors impacting the desire and the ability of Generation X buyers to acquire a Baby Boomer business.

The first three, demographic, psychographic and sociographic, are macro trends that make Xer’s unlikely to buy any business that requires capital or more than full-time commitment. .

The last three factors, Regulation, Disintermediation and Entitlements, describe why all businesses are harder to sell today than they were even ten years ago.

The presentation is a bit long (38 minutes), and the quality isn’t perfect.(My apologies for the “dings” when viewers check in. That wasn’t controllable on my end.) None the less, if you are an advisor to owners, or an owner who is planning to sell, you might want to watch this data-based approach to the market forces you’ll deal with.

“Read” my new book in 12 minutes!

Your Exit Map, Navigating the Boomer Bust is now available on Amazon, Barnes & Noble and wherever books are sold. It was ranked the #1 new release in its category on Amazon, and is supplemented by free tools and educational materials at www.YourExitMap.com.

Now, we have a really cool 12 minute animated video from our friends at readitfor.me that summarizes the book, and helps you understand why it is so different from “how to” exit planning tomes. Take some time to check it out here. Thanks!


After the Exit; “Nothing Will Change”

“Nothing will change.” It is almost de rigueur for an acquirer to include that in his or her opening comments to the incumbent staff of a just-purchased business. Sometimes it is the seller’s attempt at making folks feel better. “Don’t worry. They promised me that nothing will change.”

In the moment, it seems like a calming thing to say, a confidence builder for the employees who have just been informed that they have a new boss. In the long run, it can cause more problems than it solves.

Everything Changes

In any company, change is ongoing. Employees are asked to learn additional skills. Systems are upgraded. Procedures are rewritten. People are promoted or terminated. Customers leave, or (hopefully) big new accounts with new requirements are landed.

No experienced business owner in his or her right mind would ever promise employees that “Nothing will change.” Change is part of the landscape, and adjusting to it is inherent in keeping the business growing and relevant. Employees accept that fact unconsciously, because it’s always been part of the landscape.

Of course, when an acquirer says “Nothing will change,” he means today. There will be new procedures. New reporting relationships will have to be worked through. Software will be modified, or even discarded for the acquiring company’s preferred systems. And eventually, some employees will be promoted or terminated based on their ability to accommodate those inevitable changes.

“Nothing will change” is a license for employee dissatisfaction. They have to learn a new telephone system. (“He lied. This is a big change.”) All invoicing will be done through the central office. (“She lied. This is a massive change.”) Job descriptions and incentives will be adjusted to match the parent company’s. (“He lied. Everything is changing!”)

Demystify Change

The appropriate soother for acquisition anxiety is the truth. “I know this is a big change. You’ve faced great changes in this company before (get some examples from the seller) and your ability to adjust and succeed is what makes us so excited to be teaming up. We’ll take things slowly to start, and work with you so that our integration will be as painless as possible.”

There are no magic words that can completely eliminate employee concern. Dealing with it by promising something that isn’t true is just incurring a long-term cost for a very short-term benefit.